HR OPERATIONS GUIDE
Cash Drawer Shortage Procedure: A Factual Handoff for Retail Managers
Handle a cash drawer shortage with a secure recount, clear records, manager review and lawful payroll escalation, without jumping to conclusions.
Important: This guide provides general operational information, not legal advice. Employment requirements vary by location, industry, workforce, and situation. Confirm current requirements with qualified HR or legal professionals.
The register report shows one amount. The cash count shows another. A cashier is ready to leave, a second employee needs the drawer and the shift supervisor has customers waiting.
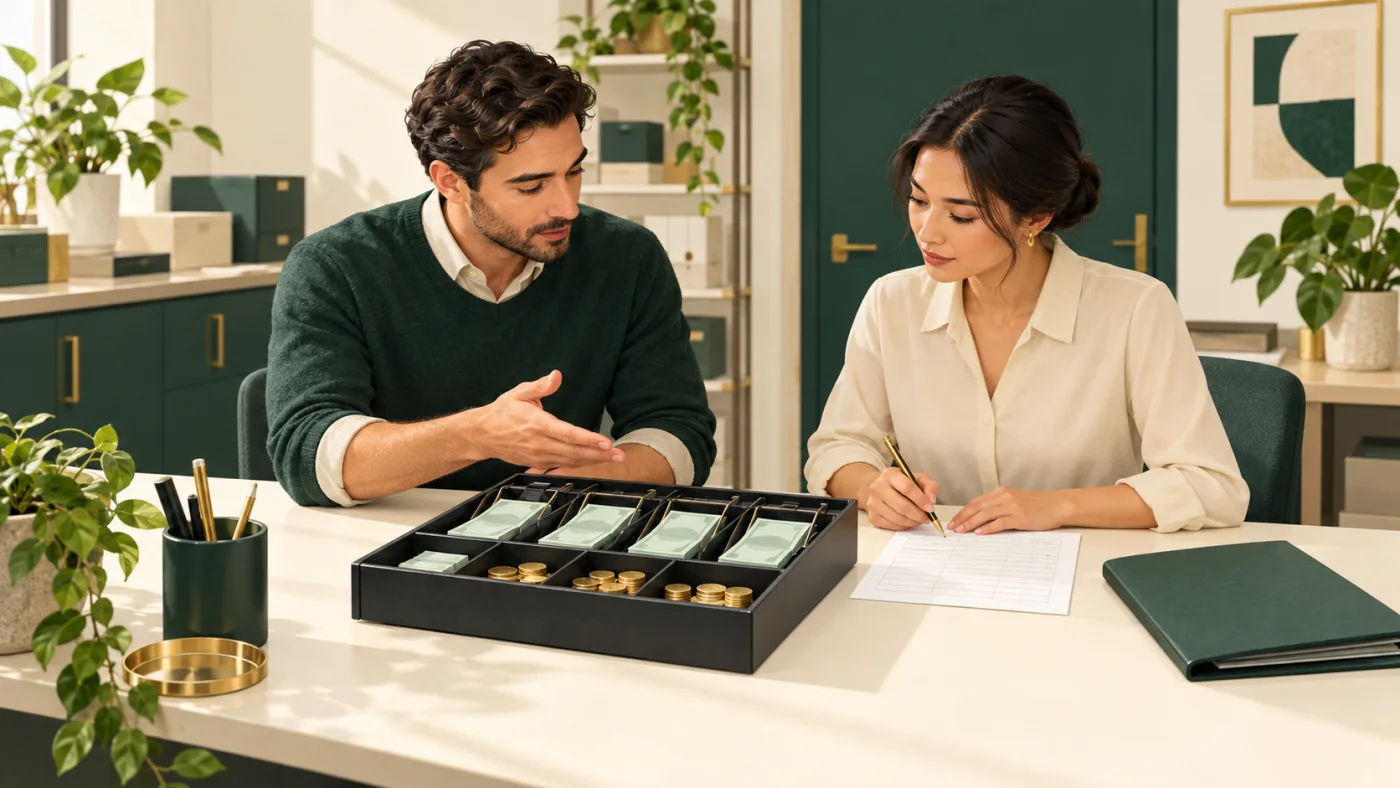
A clear cash drawer shortage procedure helps the team preserve the facts while the responsible manager reviews the difference. It should explain how to secure the money, verify the count, record the discrepancy and hand off the unresolved work.
The procedure also needs a firm boundary around pay. A short drawer does not give a supervisor automatic authority to take money from an employee's wages or demand cash from their wallet. Wage restrictions and the organization's approval process must be reviewed separately.
The workflow below is a suggested starting point for a retail business. Adapt it to your cash controls, point-of-sale system, security procedures and applicable law before using it.
Secure the drawer and identify the reporting period
Follow the store's approved process for moving the drawer to a secure counting location. Keep customer access, unattended cash and interruptions out of the count as far as the procedure allows. If there is an immediate security threat, follow the emergency process instead of continuing routine reconciliation.
Before comparing figures, confirm that the physical cash and the report cover the same drawer and period. Note the register identifier, shift or session and the person responsible for the count. Check whether a handover, cash pickup or change-fund movement occurred.
Do not mix the drawer with another till to make the totals agree. Preserve the separate records so the reviewer can understand what each amount represents.
Recount through the approved process
A second count can help identify a counting mistake, provided it is done consistently and recorded accurately. Use the store's required witness or second-reviewer process. If the policy requires another person and none is available, escalate rather than signing on their behalf.
Record the actual denomination totals. If the first and second counts differ, retain enough information to explain the correction. Do not repeatedly alter a total without recording how it changed.
Then check the expected-cash calculation through the authorized system or report. Relevant items may include the opening float, recorded cash sales, approved refunds, paid-outs and cash drops. The exact calculation depends on how the business configures and uses its system.
The cashier should not create a refund, void a transaction or change a tender type simply to remove the difference. Any correction needs the appropriate review and a truthful record.
Write down the difference without guessing the cause
Use neutral language that separates the amount from the explanation. A practical discrepancy record might include:
- Store, register and shift or session identifier
- Expected cash according to the applicable report
- Actual count and any verified recount
- Difference, clearly marked as an overage or shortage
- Relevant cash movements or transaction references
- People who counted or reviewed, and when
- Unresolved questions and the next responsible person
For a fictional example, suppose the report expects $500 after recorded cash movements and the verified count is $480. The initial finding is a $20 shortage. That arithmetic does not establish who caused it or whether a transaction, count, transfer or another issue explains it.
An employee may offer context, such as an interrupted handover or a cash drop awaiting review. Record what was reported and identify it as unverified until checked. Avoid turning a possible explanation into an admission or an accusation.
Keep the review within authorized channels
Send the discrepancy to the manager or owner designated by policy. Include the relevant report references and identify where the cash and supporting records are secured.
If further review is needed, assign a person to it. That may involve checking approved point-of-sale logs or involving the finance, HR or loss-prevention contact. Access to records, recordings or employee information should follow the organization's permissions and investigation procedures.
Keep the conversation private. Publicly accusing an employee or discussing speculation in a store-wide message makes a factual review harder. A shortage alone should not become the basis for an unsupported statement that someone stole money.
Where the count crosses a shift change, tell the receiving manager exactly what remains open. “Manager notified; cash secured; one transfer record awaiting review” is more useful than “drawer issue handled.”
Route pay questions to the qualified owner
The U.S. Department of Labor explains that deductions for employer-benefit costs cannot reduce covered employees' earnings below required minimum wage or overtime compensation. Its examples include an unlawful requirement that a minimum-wage cashier repay a drawer shortage. Requiring cash reimbursement instead of a wage deduction does not avoid those federal protections. DOL wage-deduction guidance.
State requirements also matter. For example, the Texas Workforce Commission explains that deductions outside specified legal exceptions must be lawful and specifically authorized in writing. An employee's signature does not make an otherwise unlawful deduction valid. Texas Payday Law deduction guidance.
These summaries do not decide whether any particular deduction is lawful. Have the qualified payroll, HR or legal owner review the facts and applicable rules. Do not ask a cashier to cover the difference on the spot or assume a cash-handling acknowledgment authorizes repayment.
Finish with an outcome and any needed training
Close the review with the verified finding, any authorized record correction and the appropriate employee communication. Preserve an unresolved outcome honestly if the available evidence does not explain the difference.
If the review identifies a process or training gap, make the follow-up specific. An employee may need practice recording a cash drop; a manager may need a clearer handover check. Do not treat every discrepancy as proof of a training failure, and do not use a completion checkbox as a finding of responsibility.
OdyHR can help connect employee training completion, manager follow-up and evaluations. The cash count and financial reconciliation should remain in the business's approved systems. Contact OdyHR to discuss the training handoff using fictional examples, without sending till records or confidential employee information.
AUTHORITATIVE REFERENCES